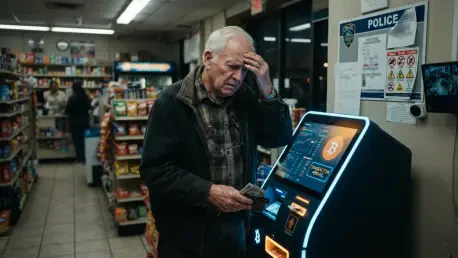
The rise of cryptocurrency ATMs has been accompanied by a documented explosion in sophisticated financial crimes that specifically target older demographics. What was once seen as a novel gateway for the unbanked has rapidly mutated into a point of extreme friction between the fintech industry and law enforcement agencies. According to data released by the FBI for 2025, consumer complaints regarding these physical kiosks skyrocketed by 58 percent compared to previous periods, resulting in financial losses exceeding 388 million dollars. This dramatic surge in fraud has forced a radical reevaluation of how these machines are classified in the public sphere. No longer viewed simply as retail convenience tools, these kiosks are now under intense scrutiny as regulators attempt to bridge the gap between innovation and the urgent need for public safety protections. These machines represent a unique challenge for investigators who are often left without a clear paper trail in hand.
The Mechanics of Financial Fraud
The methodology of these scams relies heavily on psychological manipulation and the exploitation of perceived authority. Criminals frequently initiate contact by posing as representatives from federal law enforcement, the IRS, or the fraud departments of major banking institutions. By manufacturing a state of panic, these actors convince their targets that their assets are compromised or that they are under immediate legal threat. The victim is then directed to convert their liquid cash into cryptocurrency through a local kiosk to secure their funds or pay a fabricated fine. Because these machines exist outside the traditional banking ecosystem, scammers are able to coach their victims through the process in real-time, often remaining on a voice call throughout the entire transaction. This direct line of communication effectively neutralizes standard on-screen warning messages, as the victim is instructed to ignore them as part of a protocol required to resolve their immediate crisis.
Impact on Local Law Enforcement
Once the physical currency is inserted and the digital transfer is finalized, the decentralized nature of the blockchain ensures that the transaction is irreversible and nearly impossible to trace in a timely manner. Unlike traditional wire transfers, which can be flagged or reversed by institutions, crypto kiosk transactions are settled instantly on the ledger. Funds are typically moved through a series of hop addresses across international exchanges within minutes, placing the assets far beyond the jurisdiction of local law enforcement. This technical reality has devastated communities, leading cities like Spokane and Layton to implement full moratoriums after recording millions in localized losses. Local officials have argued that the machines provide a uniquely dangerous loophole for organized crime, as they allow for the rapid laundering of illicit funds without the oversight required at a bank branch or traditional credit union, making recovery efforts nearly impossible for victims.
Regulatory Strategies and Transaction Caps
Legislative bodies across the United States have adopted a bifurcated strategy to address these risks, with some states favoring strict oversight while others move toward total prohibition. States like North Dakota and California represent the regulatory path, where new laws have introduced daily transaction caps of 2,000 dollars per user to mitigate the scale of potential losses. These jurisdictions also mandate that kiosk operators provide live, human-led customer support during peak operating hours to assist users who may be undergoing a fraudulent transaction. Furthermore, operators are increasingly required to integrate blockchain analytics software designed to flag and block transactions sent to high-risk wallet addresses associated with known criminal networks. This model seeks to preserve the availability of the cash on-ramp for legitimate users who may be underbanked while simultaneously stripping the machines of the anonymity and speed that criminals find most attractive.
Global Trends Toward Total Prohibition
In contrast, a growing coalition of jurisdictions has determined that the inherent risks of these machines far outweigh their limited utility for the general public. Indiana set a major precedent by enacting a comprehensive statewide ban earlier in 2026, a move that was quickly echoed by legislatures in Vermont and Minnesota. In Tennessee, the operation of an unlicensed crypto kiosk has even been escalated to a Class A misdemeanor, signaling a zero-tolerance policy toward the industry. This trend toward prohibition is not confined to the United States; internationally, the United Kingdom and Singapore have effectively dismantled their domestic kiosk networks by refusing to grant operating licenses. The velocity of this legislative shift is remarkable, with eighteen states passing new kiosk-related laws within the first six months of 2026 alone, reflecting a global consensus among lawmakers that the current unregulated status quo is entirely unsustainable for modern consumers.
High Markups and Predatory Pricing
Beyond the threat of scams, crypto ATMs present a significant economic disadvantage to consumers through predatory pricing and a lack of standard financial safeguards. While reputable online exchanges typically charge transaction fees ranging from 0.1 percent to 1.5 percent, physical kiosk operators frequently impose markups that can reach as high as 20 percent per transaction.